The Gap Between Identified and Realized Savings
Most procurement programs do not fail at the negotiating table. They fail between the negotiating table and the P&L.
A sourcing event concludes. A new contract is signed. The savings are "booked" in a tracker. But six months later, the savings do not appear in the operating results. The business moved on; the supplier went back to old behavior; the PO process never changed.
This gap — between identified opportunity and realized EBITDA impact — is the defining failure mode of procurement transformation. We have seen it in every sector, at every company size. And it is entirely preventable.
Why the gap exists
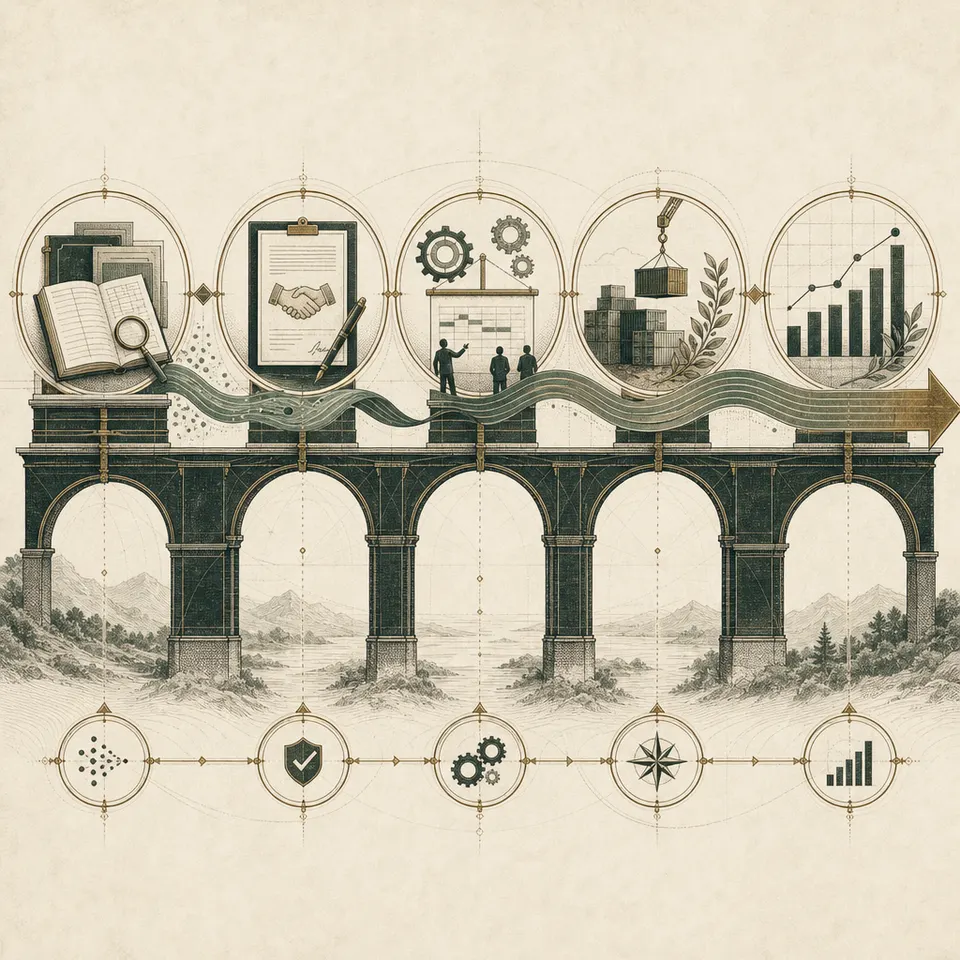
The identified savings stage is where most programs declare victory. An analyst models a 12% reduction in freight costs. A category manager negotiates a new rate card. Leadership celebrates. But identification is the beginning, not the end. Between identified and realized, there are four more gates:
- Validated: An operator has stress-tested the model against actual volume, mix, and delivery requirements. The savings survive contact with operations.
- Contracted: A signed agreement locks in the economics. The new rate applies to real purchase orders.
- Implemented: The buying behavior has changed. Purchase orders route to the right supplier at the negotiated price. Maverick spend is closed off.
- Realized: The savings appear in the operating results. The P&L reflects the change. The investment thesis holds.
Each gate has its own failure mode. Validated savings can collapse when the volume assumption is wrong. Contracted savings vanish when the legacy supplier relationship bypasses the new agreement. Implemented savings erode when the ERP is never updated. Realized savings disappear when the baseline was wrong to begin with.
The control system that closes the gap
VPP's Sourcing Control System is built around this reality. Every opportunity is assigned a stage — not as a status update, but as a governance commitment. Moving from identified to validated requires an operator sign-off. Moving from contracted to implemented requires a documented change to the purchasing process. Moving from implemented to realized requires a verified P&L entry against a clean baseline.
The baseline is everything. A savings claim without a defensible baseline is a story, not a result. We establish baselines at the start of every engagement — documented, agreed, and tied to an owner who will be accountable when the board reviews the quarter.
What this means in practice
If you are a PE sponsor reviewing a portfolio company's procurement program, ask one question: of the savings in the tracker, how many are realized versus identified? A well-governed program will have a clear answer and a clear timeline. A program that cannot answer the question has a gap problem.
If you are a CPO or COO, the control system is your accountability mechanism. It is how you tell the board that the savings are real — not as a matter of trust, but as a matter of evidence.
NEXT STEPS
CLIENT PROOF
Global Spend Visibility — Fortune 500 Manufacturer
Have a question about The Gap Between Identified and Realized Savings? Tell us where it stands in your business and an operating partner in Global Strategic Procurement will follow up.
DISCUSS THIS TOPICVANTAGE POINTE PARTNERS — OPERATOR-LED ADVISORY